Picking Our Pockets

As I mentioned in my last post, the CBO presented their analysis of current economic conditions and future projections. The CBO is careful to note that ten year projections should be treated cautiously. While the CBO’s short term forecasts can be fairly accurate, their long term forecasts are sometimes far off the mark.

Below is a graph of the CBO’s assumptions in making their forecast for 2020. (Click to enlarge in separate tab)

Individual income taxes as a percent of total Federal revenues has never risen above 50% in the past forty years. The CBO is therefore projecting historically high income taxes during the next decade. But more disturbing in their 2020 projections is that corporate income taxes are relatively low.  The chart below shows the historical percentages that individual and corporate income taxes have been as a percentage of total revenue.

Over the past 40 years, individual income taxes have averaged 46% of federal revenues. Corporate income taxes have averaged 12%. Why is the CBO projecting such a shift of the tax burden from corporations to individuals in the next decade?

Lien On Me

Jerry sent me a link to a story of legal cruelty documented by the Huffington Post Investigative Fund.  Large banks, including JP Morgan Chase and Bank of America, are buying up blocks of tax liens for delinquent property taxes, adding on exorbitant legal and interest fees, which they collect when the homeowner is forced to sell.  In one example, JPMorgan collected $12,000+ for a delinquency of less than $1000 on a $67,000 house.

What can we do?  Some cities have passed laws that prevent the sale of tax liens which are less than a minimum – a $1000, for example.  Check with your city or county to see if it has such a law.  If not, write your reps to get such a law passed.

I’m too sickened to comment further.

Unemployment Rollercoaster

At the end of September, the Congressional Budget Office (CBO) appeared before the Senate Budget Committee and presented their outlook on the economy, the deficit, and unemployment. (Click to enlarge in separate tab)

Source:  Congressional Budget Office (Click on Director’s Slide Show)

The recessions of 1980 – 81 and 1982 – 83 were really one long recession.  A several month uptick between the two recessions is the only thing that separates them.  It took several years before the National Bureau of Economic Research had enough firm data to call it two separate recessions.  I will call it a “recessionary period.”

Although this recession officially ended in June 2009, the persistently high unemployment, similar to the levels of 1980 – 1983, makes the present period an equally severe period.  But what makes the current malaise truly stand out is the rate of the long term unemployed, as shown in the graph below.

What surprised me is that men consistently suffer much higher levels of unemployment in tough times even though they are only slightly more than half of the workforce.  According to the Dept of Labor, women made up 46.8% of the workforce in 2009.  This is probably due to the greater number of men workers in the construction field, which generally suffers heavily during recessions.

For many men younger than 50 in the construction trades, these past two years may be the wake up call – that they need to build a more versatile skill set; that they can’t rely on a high school education and a learned trade skill to get them by; and in good times, it is wise to put some of the beer, boat and truck money in a savings account.

Social Security Myths

Previously, I took a closer look at the conservative “myth” that reducing tax rates raises tax revenue. This week I’ll look at a fiction frequently trotted out by those on the left: the rich get off easy on their contributions to Social Security.

A recent example is a Senate hearing (32 minutes into the tape) in which Tom Harkin, the Democratic Senator from Iowa, states that, because of the $106K cap on earnings subject to the Social Security tax, people making $400K paying Social Security tax on 25c out of every dollar while most people in this country pay Social Security tax on every dollar they make. This is true. But what Senator Harkin neglects to mention is that Social Security benefits are also capped.

Let’s look at 3 examples: Joe, making the median annual earnings of $40K; Sally, earning $100K and in the top 5% of earners; and Marilyn, making $150K. Each of them was born in 1950 and will retire at their full retirement age in 2016.

Using the Social Security Administration’s (SSA) benefits calculator , Joe will get a full retirement monthly benefit of $1184 when he retires. Using the default growth rates of income, the SSA estimates Joe’s lifetime income at $848K. Sally will get a monthly benefit of $2100 on estimated lifetime earnings of $2,119K. Sally has contributed 250% more than Joe but will receive less than double the benefit. Marilyn will receive a monthly benefit of $2434 based on a lifetime earnings estimate of $2,623K, triple Joe’s earnings.  Because of the social security contributions cap (currently about $106K), Marilyn has not contributed three times what Joe has contributed, but she has still contributed more than 2.5 times what Joe has contributed.  However, Marilyn gets only double the benefit that Joe receives.

In short, Social Security is both a safety net and an income redistribution scheme. An American Institute of CPAs (AICPA) report notes that Social Security was originally designed as a prepaid pension plan so that benefits received were dependent on contributions made by each person. That original design was amended a few years later to turn Social Security into a “pay-as-you-go” system where retiree benefits were paid for by the taxes of current workers. Although benefits were indexed to contributions, those who earned less received far more benefits in proportion to their contributions. Social Security thus became a hybrid income redistribution scheme for retirees. You can read a colorful history of pensions at the SSA web site.

Few conservative or liberal politicians readily acknowledge the income redistribution aspect of Social Security. The program has been “sold” to taxpayers as though it was an insurance product, similar to an annuity policy that anyone can buy from an insurance company. The only difference is that the federal government is the insurance company. Regardless of what one feels about the income redistribution part of Social Security, it has reduced “the poverty rate among the elderly from 35% in 1959 to 10% in 2003, the lowest of any adult group.” (Source) A recent report by the Census Bureau shows that poverty rates for seniors are 2/3 to 3/4 that of adults in general. Have we gone a bit too far in helping seniors? Poverty rates for children are at a shocking 20% plus, but few politicans dare to propose reducing benefits for the elderly to help children. Seniors vote. Children don’t. Because seniors have been convinced that Social Security is like an annuity insurance program, many seniors balk at any reduction in benefits. They are convinced that they paid in full measure for the benefits they receive.

As the examples above show, both Marilyn and Sally pay a portion of Joe’s benefits. Yet Joe probably thinks that he has earned every penny of his benefits because he “paid into the system.” This misconception is likely to make changes to Social Security benefits extremely difficult. Those who are well off know that they contribute far more into the system than they receive. Those who are less well off will prefer to “soak the rich” even more rather than give up benefit increases.

For those of you who like wrestling, you may be able to see in coming years the (cue up the loud music) “Social Security Smackdown” on a cable channel.

Government Vacuum

Imagine a world where a quart of milk costs the same in 1950 as it does in 2000. That’s the imaginary world of inflation adjusted or constant dollars, which adjusts current dollars by the Consumer Price Index (CPI). Although imperfect, constant dollars gives us a way to compare apples to apples.

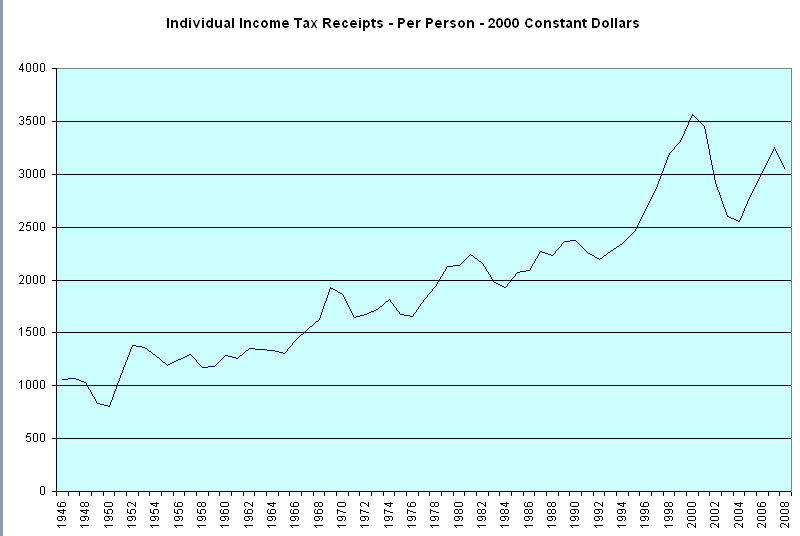
Tax cuts and increases have been a hot topic of political discourse leading up to the elections. In my earlier blog, I showed the income taxes (in inflation adjusted dollars) collected over the past half century. As you may have noticed, those taxes kept rising. With a growing population, it is natural that income taxes collected should continue to rise. What may not be so apparent is the rise in taxes collected PER PERSON.

In the table below (click to enlarge in a separate tab), I divided Office of Managment and Budget (OMB) data on individual income taxes by annual population figures from the U.S. Census Bureau to come up with a per person average of income taxes collected.

Per person means everyone! The federal government is collecting triple the amount of real money that they collected 60 years ago. If the cost per person of government was about $1000 in 1950 and it is $3000 now, are we getting triple in services from our government? Or are we getting screwed?

Political Economics

As we approach the upcoming elections we hear some favorite myths of both the left and the right.  Today I’ll look at a favorite myth that is trotted out by supply side believers on the right.

Does lowering income tax rates produce more income tax revenue?  Below is a chart of historical income tax data from the Office of Management and Budget (OMB) – click to view larger image in separate tab.  After the Kennedy era tax cuts, revenue increased.  After the Reagan tax cuts, revenue initially decreased.  The Clinton era tax increases clearly show an increase in revenues.  The Bush era tax cuts clearly show a decrease in revenues.

Does lowering or raising tax rates produce more revenue? Increases or decreases in revenue may have more to do with the economy or rising asset values (capital gains taxes) than tax rates. Still, some conservatives will continue to insist that lower tax rates produce more revenue. The justification for their assertion is to look at TOTAL federal revenue, including social security taxes, to make their point. This is a sleight of hand argument since Social Security tax revenue is not affected by income tax rates but it is the only way that conservative supply side believers can make their point. They can only hope that their audience doesn’t look too closely at the facts – at least not until after the election.

Recession Procession

Recently, the National Bureau of Economic Research (NBER) made their official pronouncement that the recession that began in Dec. 2007 ended in June 2009. In July 2009, the Federal Reserve had issued its unofficial estimation that the recession had just ended. This latest announcement by the NBER is a statistical confirmation of what the Federal Reserve had announced over a year ago. To many individuals and businesses, however, the recession is not over. In a CNBC interview, the renowned investor and billionaire Warren Buffett stated his more common sense definition that the recession is not over until production and income get back to the levels they were before the recession started. Most would agree.

There is no clear definition of the beginning and end of a recession but the NBER’s Business Cycle Dating Committee states that a recession is “a significant decline in economic activity spreads across the economy and can last from a few months to more than a year.” The rule of thumb is two consecutive quarters of negative GDP growth. But neither the NBER definition or the rule of thumb adequately captures the effect – how it feels – of a downturn in the economy. That is because the rule of thumb is based on quarter to quarter growth or decline in GDP. If GDP were a $1 and, over a year, fell to 80¢, then rose to 85¢ in the following quarter, the economy would still be terrible but the growth in GDP would be an annualized 25%. For this reason, Buffett’s rule of thumb gives a more accurate picture.

Below is a NBER chart of real, or inflation-adjusted GDP, with Dec 2007 being the benchmark of a 100. As you can see, our economy is still below the level of December 2007. (Click to view larger image in a new tab)

The severe downturn in manufacturing and retail sales tells a more complete picture, not only of the national economy, but the state and local economies which depend heavily on sales taxes for their revenue. Total unemployment is about 16% of the workforce and, until that situation improves, there will be only sluggish growth in sales, which in turn will keep on damper on GDP growth.

Debt Power

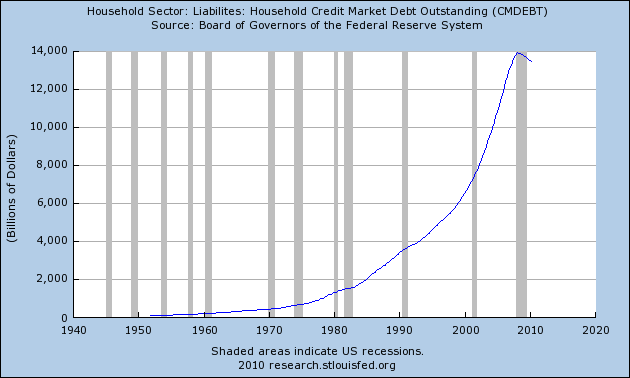
Visitors to an air show may have had the opportunity to witness the vertical take off power of an F18 fighter jet.  Flying horizontally to the ground, the jet makes an almost 90° turn and shoots up into the sky, a breathtaking show of power for spectators.  Welcome to the airshow of the last three decades.  Below is a Federal Reserve graph of household debt. (Click on any graph to enlarge)

  Aren’t you impressed with the sheer power of consumer borrowing?  Next in our air show is state and local government borrowing.

Not to be outdone, Fannie and Freddie, the government sponsored mortgage companies, show off their impressive borrowing power.

And lastly, our federal government turns on the after burners and shoots up into the debt stratosphere.  This chart does not include the almost $5 trillion of debt the federal government owes its agencies, like the Social Security trust funds, or the Federal Reserve.

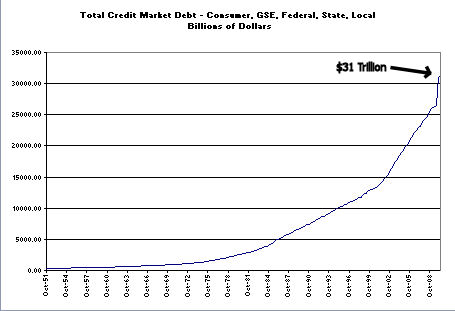
Together, we – after all, it’s our governments – are the Blue Angels of debt – or perhaps we should be called the Red Angels of debt.  Together, we have piled up over $31 trillion in debt, more than twice the national GDP. 

Even if we devoted 10% of a $14 trillion GDP to paying down all this debt, it would take over twenty years.  As any one of us knows, debt is a serious drag on savings and investment.  We can expect that the drag of this debt will be with us for many years to come.

Median and the Mean

The mean or average is a different animal than the median, yet the two are sometimes confused.  The median is the middle of a data set – 50% of the data are below that middle, 50% are above.  The median housing price for an area is more representative of the area than the average price, which is skewed higher by really expensive homes.

A revealing look at an overall trend in wages is the following table from the Social Security Administration, showing the growing disparity between the median wage and the average wage for the past two decades.  Adjusting for inflation, the median wage, in 1990 dollars, has increased 11% from $14,498 to $16,095 ($26,514 in 2008 dollars).  The average wage, however, has increased 19% – from $20,172 to $24,071 ($39,652 in 2008 dollars).  In the far right column of the table, we can see the ratio of median to average wage declining, showing that the top half of income earners are seeing significantly better progress than the lower half.

Stock market wags repeat the mantra that a rising tide raises all boats.  The tide of the past two decades has left half of the boats stuck in the mud.  

Poverty

This past week the Census Bureau released their annual estimate of median income and poverty.  For 2009, the poverty level increased from 13.2% to 14.3%.  Economists and policy makers have been debating the definition and calculation of poverty since the introduction of the social welfare programs of the Great Society  in the 1960s.  Since the mid-nineties, many have called for a revision of the calculations that gives weight to cost of living variances in the country.  To most people, that makes sense.  Because it makes sense, it is a political hot potato.  The thresholds of poverty are used to determine eligibility for a number of federal programs.  Adjusting  those thresholds would qualify many more people for assistance in some areas, particularly larger metropolitan areas, while disqualifying some in rural areas where the cost of living is less.

How does the Census Bureau measure poverty?  They include all cash income but non-cash items like Medicaid, food stamps and housing subsidies, like Section 8, don’t count as income. (Source)  To qualify for housing assistance, the family’s income may not exceed 50% of the median income for the county or metropolitan area in which the family chooses to live.  The rent subsidy is generally the lesser of the payment standard minus 30% of the family’s monthly adjusted income or the gross rent for the unit minus 30% of monthly adjusted income.

Let’s look at two “traditional” families of four in Denver, Colorado, where wages and cost of living are only slightly above the national average. (Source)

In Family A, Dad works a regular job as a laborer for $12 an hour for 35 hours a week, slightly more than the median hours worked per week, earning about $22000 per year.  Family A’s income is at the poverty level, qualifying them for housing assistance, Medicaid, food stamps and other assistance programs for meeting their monthly bills.  Family A’s adjusted income per HUD standards is gross income less about $500 per dependent, or $20K.  They would pay 30% of that for rent, $6000, for an apt renting for about $9600 annually, receiving about $3600 in tax free income.  In addition, they would get about $325 in food stamps  per month, or another $4000 in untaxed income.  In addition, Dad would get $34 per week in Earned Income Credits, paid by his employer, for an annual total of about $1800.  Since they qualify for Medicaid, this family would have no or minimal health insurance premiums. This family would pay no federal or state income taxes but they would be subject to the FICA payroll tax of about $1650 per year. This family’s net effective income is about $30K.

In Family B, Dad works for $22 per hour for 35 hours a week, earning an annual gross of $40,000, about 16% – 18% less than the median household income for Denver but about equal to the median wage.  This family’s income is in the 40th percentile of Denver area income, slightly above that percentile for the country as a whole.  This family does not qualify for either  housing assistance, Medicaid, food stamps, the energy assistance program LIHEAP or the Earned Income Credit. Dad pays 50% of a $1200 HMO family medical plan which his employer offers, an annual cost of $7200.   This family pays about $120 per year in federal and state income taxes and $2500 in FICA taxes.  This family’s net effective income is also $30K.

Two families – one at the poverty level of income, one slightly below the median income level – have approximately the same level of disposable income.  Either there are a number of families classified as poor who really aren’t poor or about 40% of the households in this country are effectively at or below the poverty level.